Marks vs. Prices, Technology and the capital cycle
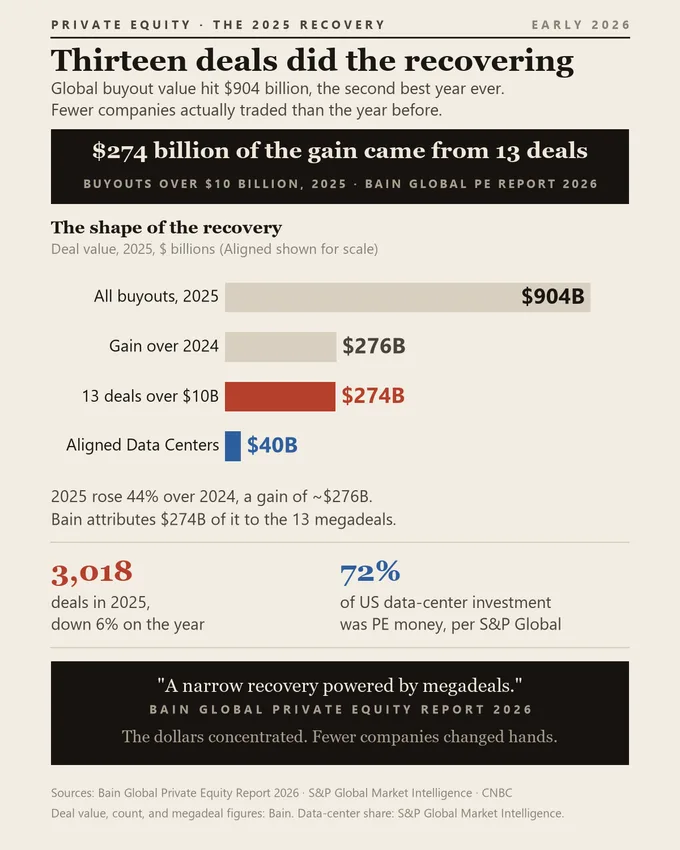
13 buyouts over $10BN made $274BN of the $276BN gain in 2025 deal value
By Jeff Baehr, Founder & CEO, Praxis Rock Advisors
In brief
Global buyout value reached $904BN in 2025, up 44%, while deal count fell 6% to 3,018. Bain attributes $274BN of the gain to the buyouts over $10BN, with data centers the most visible share. A GP holding an ordinary company should not price its exit to that market.
The 2025 deal market didn't recover. Thirteen deals did.
Bain's 2026 report counts $904 billion of global buyout value last year, the second best in the industry's history. The recovery headline writes itself, and it is the easy number to build a 2026 plan on.
Now subtract thirteen deals. Value grew 44% over 2024, about $276 billion, and Bain attributes $274 billion of that gain to the buyouts over $10 billion. Thirteen deals were, in effect, the entire recovery.
Source: see Sources below. As of July 2026.
| Figure | What it shows |
|---|---|
| $904BN | Global buyout value, 2025 |
| $276BN | Gain over 2024 (44%) |
| $274BN | Of the gain from 13 deals over $10BN |
| 3,018 | Deals in 2025, down 6% on the year |
| 72% | Share of 2025 US data center investment that was private equity money |
Deal count actually fell 6%, to 3,018. Bain's own words for the shape of it: a narrow recovery powered by megadeals.
Fewer companies changed hands than the year before. The dollars concentrated.
Look at where. S&P Global Market Intelligence counts $45.7 billion of private equity money into US data centers in 2025, 72% of everything invested in the sector.
Aligned Data Centers alone went for roughly $40 billion of enterprise value, the largest data center deal on record, with Nvidia, Microsoft and xAI standing alongside the financial sponsors.
That is not a broad private equity recovery. That is concentration, and its most visible face is the AI buildout clearing through private equity structures.
The distinction decides real behavior. A GP holding an ordinary industrial or services company reads the headline, concludes the bid is back, and prices the exit to a market that exists for data centers and near-hyperscale software, not for their asset.
Waiting for the headline market to arrive at their door is how holds stretch another two years while fees run.
The sorting is already visible in the numbers. Value at record levels, count still falling: the market is paying up for a narrow class of assets and passing on the rest.
A recovery that reaches the median company shows up in the count, not just the value. This one has not.
GPs get two honest reads. If your portfolio touches the buildout, the exit window is genuinely open, and it is the best seller's market that class will see. If it does not, your market has not recovered, and pricing like it has is the same entry price mistake in exit form.
My sense is the 2026 league tables make this split undeniable.
Which market are your marks assuming you are in?
The research behind this
- Bain & Company, Outlook: gaining traction, Global Private Equity Report 2026, 2026.
- CNBC, Nvidia, Microsoft and BlackRock group to buy Aligned Data Centers, October 15, 2025.