Marks vs. Prices, LPs, returns and liquidity
Bank CEOs say sponsors are stuck on marks; price each 2021 deal against today's bid
By Jeff Baehr, Founder & CEO, Praxis Rock Advisors
In brief
In the same October week, the CEOs of Morgan Stanley and Goldman Sachs described sponsors holding assets above what the market will pay. In an April poll cited by Bain, most LPs said they start to lose confidence in a GP when a full exit prices more than 5% below the last mark. Take the markdown in the quarterly letter, not in the exit memo.
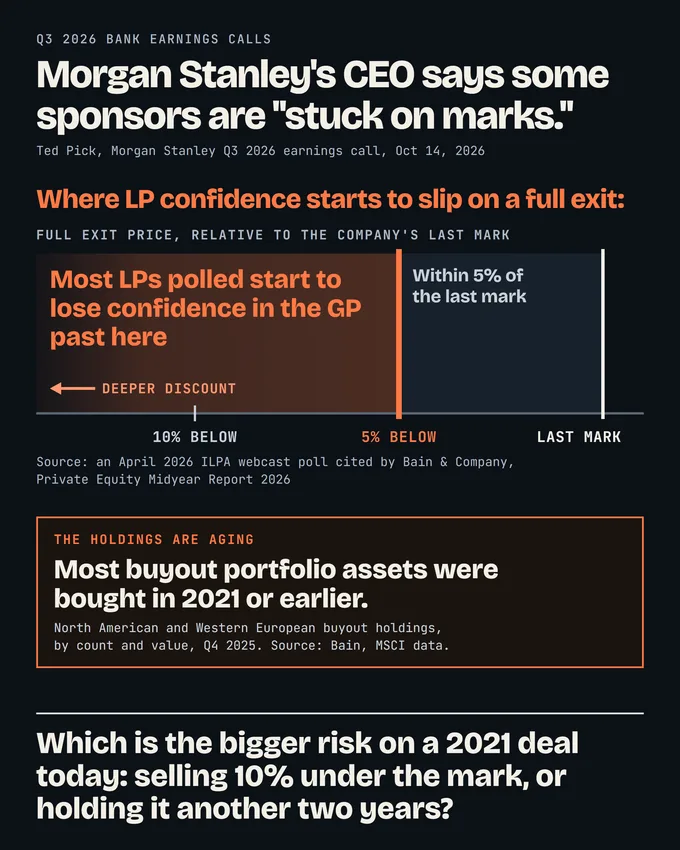
Morgan Stanley's Ted Pick says some sponsors are "stuck on marks."
You set the last mark, and in an April ILPA poll cited by Bain, most LPs said they start to lose confidence in a GP when a full exit prices more than 5% below it.
Pick wasn't alone this week. Goldman's David Solomon said a lot of what sits in sponsors' 2020 and 2021 vintages is "still marked higher than where it can be monetized," and sponsors wait "because that's the way the incentive system works." Citi's Jane Fraser said sponsors "continued to sit on aged assets."
Source: see Sources below. As of October 2026.
| Figure | What it shows |
|---|---|
| 5% | Discount to the last mark past which most LPs polled start to lose confidence |
| 10% | The exit discount the post weighs against two more years of holding |
| 2021 | Most buyout holdings at the end of 2025 were bought in this year or earlier |
Solomon didn't spell out the incentive. Bain's midyear report names one: "If I realize average outcomes, then I could be dead in fund-raising." My read: for a GP raising its next fund, it's less the fees and carry than the LP meeting where one exit 10% under the mark becomes the whole conversation.
Bain's own report cuts the other way: companies have tended to exit at a premium to their next-to-last quarterly mark, and Bain says that still broadly holds. But GPs chose those companies to sell, and Bain says many are reluctant to bring anything but their best-placed companies to market. I'd read those exits as survivors.
Holding has a cost too. At the end of 2025, most North American and Western European buyout assets dated from 2021 or earlier, and Bain warns that "the longer they sit, the more LPs question whether their marks truly reflect intrinsic value."
My call for lower-middle-market and mid-market GPs: price every 2021 deal against today's bid, not the mark. Hold the ones where the return from here beats taking that bid. Sell the rest before they age into the fund's final years.
And tell your LPs first. The poll measures the haircut against that mark. Take the markdown in the quarterly letter, not the exit memo. LPs take the same loss either way, and it stings less than a surprise.
In July I wrote that managers who sell at real prices this cycle raise the next fund, and managers defending 2021 marks become the tail. This week Pick and Solomon described sponsors holding above what the market will pay. In my read, that's the second group.
Which is the bigger risk on a 2021 deal today: selling 10% under the mark, or holding it another two years?
The research behind this
- Bain & Company, Private Equity Midyear Report 2026, 2026.
- Morgan Stanley via The Motley Fool, Morgan Stanley Q3 2026 earnings call transcript, October 14, 2026.
- Goldman Sachs via The Motley Fool, Goldman Sachs Q3 2026 earnings call transcript, October 13, 2026.
- Citigroup, Third quarter 2026 earnings call transcript, October 2026.