Marks vs. Prices, Private credit and lending
Delaware Life's restated related party book is about 4.5x its capital
By Jeff Baehr, Founder & CEO, Praxis Rock Advisors
In brief
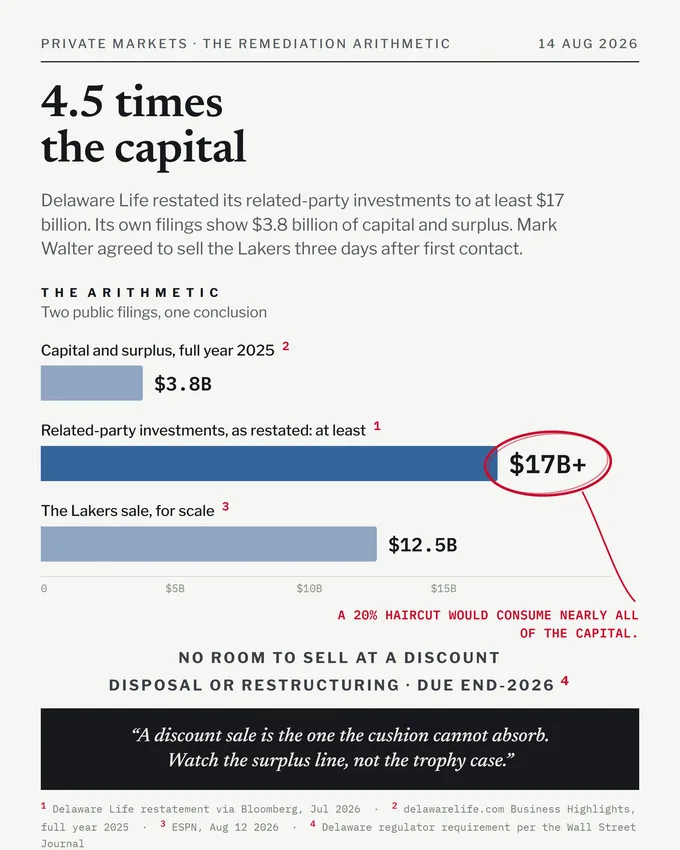
Delaware Life restated its related party investments from $1.4BN to at least $17BN, at least 39% of invested assets. The insurer reports $3.8BN of capital and surplus, so each point of discount on that book costs 4.5% of its capital. That arithmetic, more than the $12.5BN Lakers sale, sets the exits.
Almost 40% of an insurer's investments sit inside its owner's empire. Start there, not the Lakers.
I'm a Lakers fan, so I've followed this closely. Then I read the Delaware regulator's examination report and the insurer's own statutory filings.
The headlines, per ESPN: Josh Kushner and Bob Iger are buying the Lakers at $12.5 billion, a record, three days after first contact, a year after Mark Walter paid $10 billion.
The backdrop, per Bloomberg: Manhattan prosecutors and the SEC are examining whether Walter's insurers failed to disclose that private credit backed other parts of his empire. Grand jury subpoenas arrived in February.
An internal review, the companies said, found reporting errors, and Delaware Life restated its related-party investments from $1.4 billion, 3% of invested assets, to at least $17 billion. At least 39%.
Source: see Sources below. As of August 2026.
| Figure | What it shows |
|---|---|
| $3.8BN | Capital and surplus, full year 2025 |
| $17BN+ | Related party investments, as restated |
| 4.5x | The restated book against capital and surplus |
| $12.5BN | The Lakers sale, for scale |
Related-party lending is legal. The rule is disclosure, and nothing reported says these loans are bad.
Here is what the filings add. Delaware's examination of this insurer, covering 2020 through 2023, published June 2025: no significant findings. A year later came the $16 billion restatement, dated end-2025.
In between, invested assets grew $16.6 billion. No filing yet says how much of the restated book existed inside the examined window.
Now the arithmetic. The insurer reports $3.8 billion of capital and surplus for 2025. The restated affiliated book is about 4.5 times that.
Every point of discount on that book costs 4.5% of the capital; twenty points would take nearly all of it. All three raters still carry A-, on negative outlook.
That prices the exits. A discount sale is the one the cushion cannot absorb.
The regulator's other option, restructuring, and the clean one, par repayment by borrowers tied to Walter, both run through him. My read: either way he refinances himself.
Bloomberg reports TWG raising cash to pay the loans down, the Lakers sale accelerating it; the Wall Street Journal reports the Delaware regulator wants the book disposed of or restructured by end of 2026.
Walter has not been charged; investigations like this can end without charges. TWG, his holding company, says it acted in good faith and is cooperating.
A 25% gain in a year needs no conspiracy. It still had to be that asset.
My sense is the $12.5 billion was never a price for a team; it was the refinancing of an empire. Watch the surplus line, not the trophy case.
The research behind this
- Delaware Department of Insurance, Examination report, Delaware Life Insurance Company, 2023, June 2025.
- Delaware Life, Business highlights, 2026.
- Bloomberg, Billionaire Mark Walter's firms probed by federal prosecutors, July 20, 2026.
- Bloomberg, Lakers owner Walter seeks cash to pay down loans amid DOJ probe, August 12, 2026.
- ESPN, Josh Kushner and Bob Iger buy the Lakers, August 12, 2026.