Marks vs. Prices, LPs, returns and liquidity
Investors asked a Blue Owl fund for $1.1BN back and will get $135MM this round
By Jeff Baehr, Founder & CEO, Praxis Rock Advisors
In brief
Holders of an estimated 39% of Blue Owl Technology Income Corp.'s shares asked to redeem, and the fund will buy back 5%, pro rata. Borrowing to pay everyone would take its debt past the legal limit for the fund. Once this round is paid, first quarter requests will be about 35% filled, and at that pace half takes about five quarters.
Investors asked a Blue Owl fund for $1.1 billion back. They'll get $135 million, for now.
The gate isn't protecting Blue Owl from its investors. It's protecting its investors from each other.
Blue Owl Technology Income Corp., a nontraded BDC that lends to tech companies and sells its shares through brokers, disclosed the requests Oct. 2. Holders of an estimated 39% of its shares asked out, most of them repeat requests. The fund will buy back 5%, pro rata.
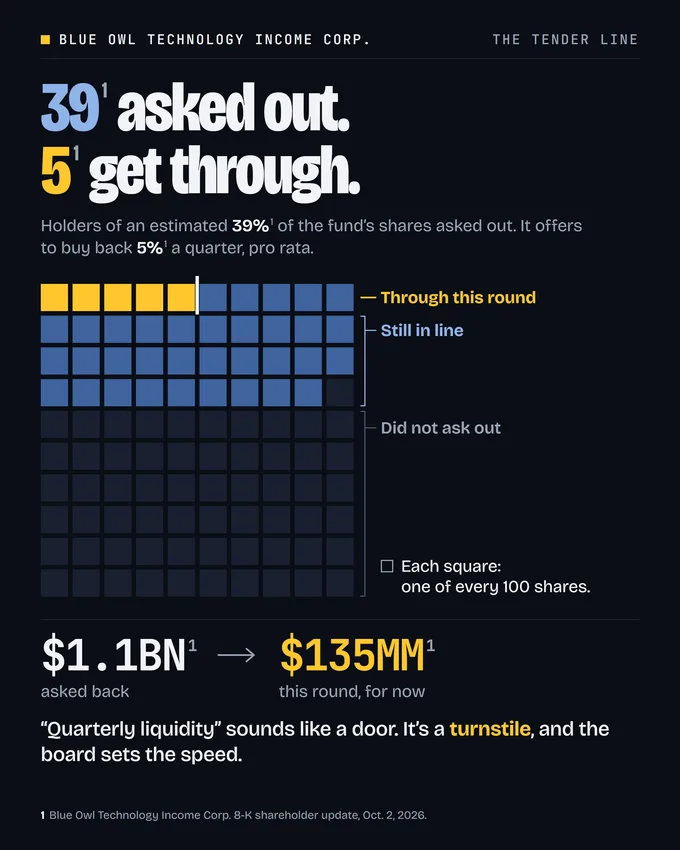
Source: see Sources below. As of October 2026.
| Figure | What it shows |
|---|---|
| 39% | Share of the fund's shares asked out (estimated) |
| 5% | Shares the fund buys back a quarter, pro rata |
| $1.1BN | Asked back |
| $135MM | Paid this round, for now |
The industry shorthand for this is "quarterly liquidity." The fund's filings are plainer. Its repurchase offers give holders "the potential for a measure of liquidity," up to 5% of shares a quarter, at the board's complete discretion.
The board has paid everyone before. In January it bought every share submitted, 15.4% of the fund. In the next tender, requests jumped to 40.4%.
Why not do it again? At June 30, most of the fund's liquidity was borrowing capacity. By my math, borrowing to clear the line would take debt from under 0.9x equity to just over 2x, past the legal limit for this fund.
Even paid in cash, a full payout would leave everyone who stays more levered.
So for anyone who sells or owns these funds, the live question is speed, not solvency. Blue Owl says that once this round is paid, first-quarter requests will be about 35% filled. At that pace, half takes about five quarters.
The one outside bid on file says what impatience might cost. In February, Saba Capital Management and Cox Capital Partners said they planned to bid for the fund's shares at 20% to 35% below NAV. No offer has been filed since.
The loans don't look like the problem. In February the fund sold $344 million of them, slices of 60 companies, at 99.6 cents on the dollar. Blue Owl says repayments have more than covered this year's three 5% tenders.
In July I suggested that redemption queues would disclose what the marks did not. So far, this one is disclosing the wrapper, not the loans.
"Quarterly liquidity" sounds like a door. It's a turnstile, and the board sets the speed.
The research behind this
- Blue Owl Technology Income Corp., Shareholder update, Form 8-K exhibit, October 2, 2026.
- Blue Owl Technology Income Corp., Form 10-Q, quarter ended June 30, 2026, August 2026.
- Blue Owl Technology Income Corp., Tender offer final amendment, January 2026, January 29, 2026.
- Saba Capital Management and Cox Capital Partners, Schedule TO-C, February 20, 2026.