Marks vs. Prices, Technology and the capital cycle
Serving each $1 of Anthropic's revenue cost about $0.31 this year, against $1.95 in 2024
By Jeff Baehr, Founder & CEO, Praxis Rock Advisors
In brief
On the numbers in Anthropic's IPO filing, serving each $1 of revenue cost roughly $0.31 in the first half of 2026 once its payments to partners are added, and $1.95 in 2024 before them. Revenue grew 14x while the compute to serve it grew about 2.3x. The open question is whether demand keeps pace with the $265.6BN of compute it has signed up for.
Anthropic's IPO story isn't the $80.7B loss. It's $0.31.
That's roughly what serving each $1 of revenue cost in the first half of this year, partner fees included. In 2024, before fees, it was $1.95.
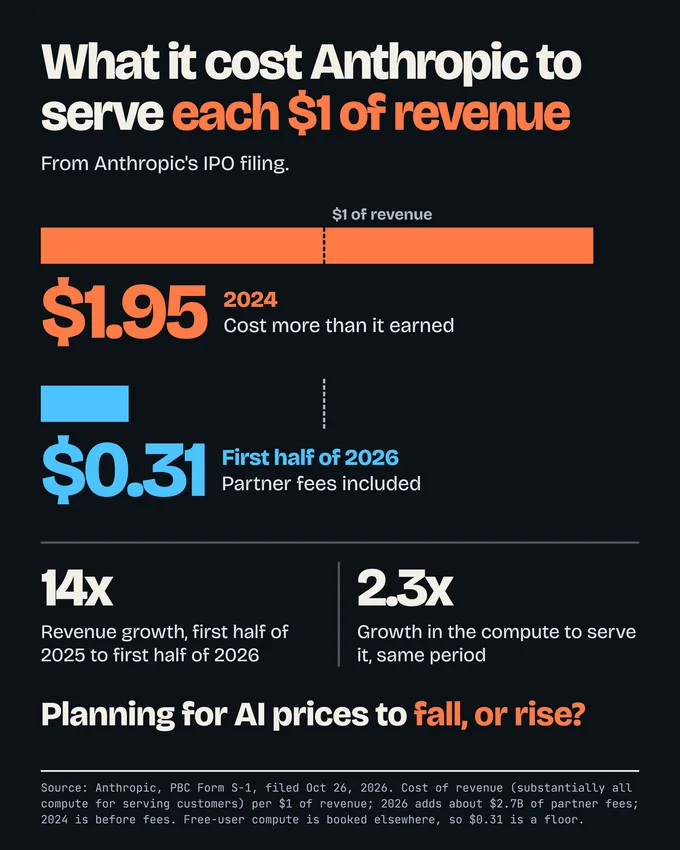
Source: see Sources below. As of October 2026.
| Figure | What it shows |
|---|---|
| $1.95 | Cost to serve each $1 of revenue, 2024, partner payments not included |
| $0.31 | Cost to serve each $1 of revenue, first half of 2026, partner payments included |
| 14x | Revenue growth, first half of 2025 to first half of 2026 |
| 2.3x | Growth in the compute to serve it, same period |
Anthropic made the filing public Oct. 26. The headlines led with the loss, but most of it is a paper charge tied to Anthropic's own rising valuation, not the cost of running the business.
About half of the $0.31 is the computing power that runs the models. The filing says its cost of revenue is substantially all compute for serving customers. I added the fees it pays the cloud platforms and other partners that sell it.
For two years the bear case on AI went like this. The labs lose money serving customers and hope to make it up on volume.
On Anthropic's own numbers, that was true in 2024. It isn't now.
Here's the engine. Revenue grew 14x from the first half of last year to the first half of this one. The compute to serve it grew about 2.3x. Scale did most of the work.
One caveat on the $0.31: the compute for free users is booked elsewhere in the filing, so treat it as a floor.
The skeptic gets one fair point, and it's a big one. Anthropic has signed up for about $265.6B of compute it must pay for over the coming years, roughly 8 years of revenue at this year's pace.
The filing says compute costs fell as a share of revenue because revenue outran compute it had already committed to buy. If demand stalls, those bills still come due.
My read: the "AI runs on a subsidy that has to unwind" story is aging badly. On serving, Anthropic is not selling below cost to buy share.
That matters to anyone building on these models. A vendor with this margin has room to cut prices.
So the question has changed. It used to be whether serving AI could ever make money. Now it's whether demand keeps pace with the compute it has signed up for. That's a growth bet with real risk, and it's the better problem to have.
If you're building on these models, are you planning for AI prices to fall from here, or rise?
The research behind this
- Anthropic, PBC, Form S-1, October 26, 2026.
- Reuters, Anthropic opens books on explosive growth and staggering costs, October 26, 2026.
- CNBC, Anthropic IPO filing: live updates, October 26, 2026.